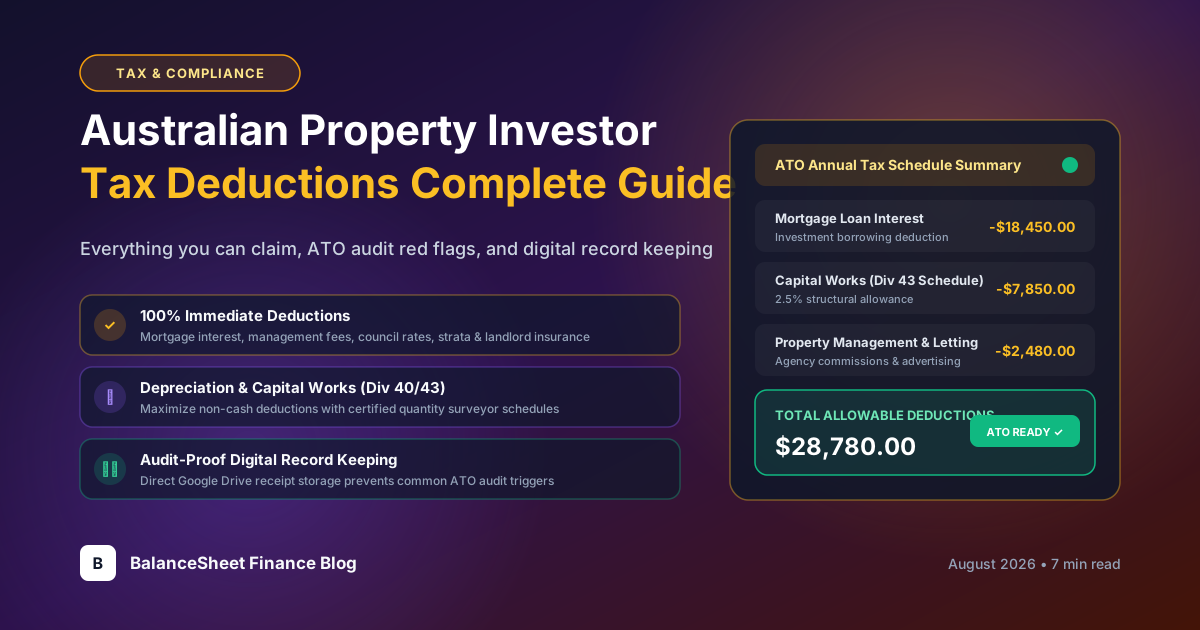
For Australian property investors, claiming all eligible tax deductions can make a substantial difference to net portfolio yields. However, the Australian Taxation Office (ATO) continues to scrutinize rental property schedules, focusing on incorrectly claimed initial repairs, private use interest, and unsubstantiated utility claims.
This guide outlines exactly what you can claim, what requires depreciation, and how to maintain an audit-proof digital trail.
#1. The Three Categories of Property Deductions
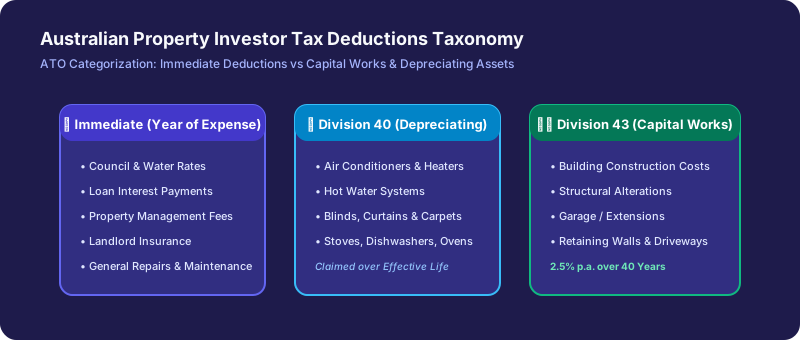
The ATO divides rental property expenses into three distinct buckets:
#1. Immediate Deductions (Claimed in Full in the Year Incurred)
Expenses directly related to the tenant's occupation and ongoing maintenance of the property:
- Loan Interest Payments: Only the interest portion on the investment debt (not principal repayments).
- Council Rates & Water Charges: Local council rates, storm water, and fixed service fees.
- Body Corporate / Strata Levies: Administrative fund levies and regular maintenance levies.
- Landlord Insurance: Building, contents, and public liability policies.
- Property Management Commissions: Monthly management fees, letting fees, and statement costs.
- Repairs & Maintenance: Fixing wear and tear (e.g., repairing a broken tile or fixing a leaking roof).
#2. Depreciating Assets (Division 40)
Freestanding items with a limited effective life (e.g. appliances, air conditioning units, floor coverings) are depreciated over multiple years using either the prime cost or diminishing value method.
#3. Capital Works (Division 43)
Structural improvements and initial renovations are claimed at a rate of 2.5% per year over 40 years from the date of construction.
#2. Common ATO Audit Red Flags & How to Avoid Them
Initial Repairs vs. Ongoing Maintenance: Purchasing a run-down property and immediately renovating it before renting is considered capital improvement by the ATO, not an immediate deduction.
#Top 4 Scrutiny Points:
- Redraws on Investment Loans for Private Use: If you redraw funds from your investment mortgage to purchase a personal vehicle or holiday, that portion of the loan interest is permanently non-deductible.
- Missing Receipts & Documentation: Credit card statements alone are insufficient during an ATO audit; tax invoices showing itemized descriptions and ABNs are mandatory.
- Holiday Homes & Private Enjoyment: If the property is reserved for personal use during peak seasons, deductions must be apportioned accordingly.
- Body Corporate Special Levies: Special levies raised for capital structural replacements (like full building repainting or balcony rebuilds) must be depreciated under Capital Works, not claimed immediately.
#3. Organizing Your Tax File Automatically with BalanceSheet
Maintaining organized folders for each property and financial year eliminates pre-tax panic:
- FY Folder Segregation: Store receipts automatically organized as
/BalanceSheet/[Address]/FY 2026-27/[Category]. - AI Invoice Tagging: Let AI extract account numbers, invoice dates, and bill amounts directly into structured metadata.
- One-Click Accountant Share: Export an itemized spreadsheet with Google Drive links for your CPA or tax agent.
Always retain rental property records for 5 years from the date you lodge your tax return.